Automatic Enrollment
Per the US Department of the Treasury, as of October 1, 2026, all eligible children under 18 with a valid Social Security Number have been automatically enrolled for a 530A/Trump account (your child did not get auto-enrolled if they will be turning 18 before the end of 2026, making them ineligible, or if you already enrolled them for a 530A account). Over 60 million children were automatically enrolled according to the Treasury, so there’s a good chance you will or already have received one of the below:
Email from information@update.ssa.gov:
Physical mail:
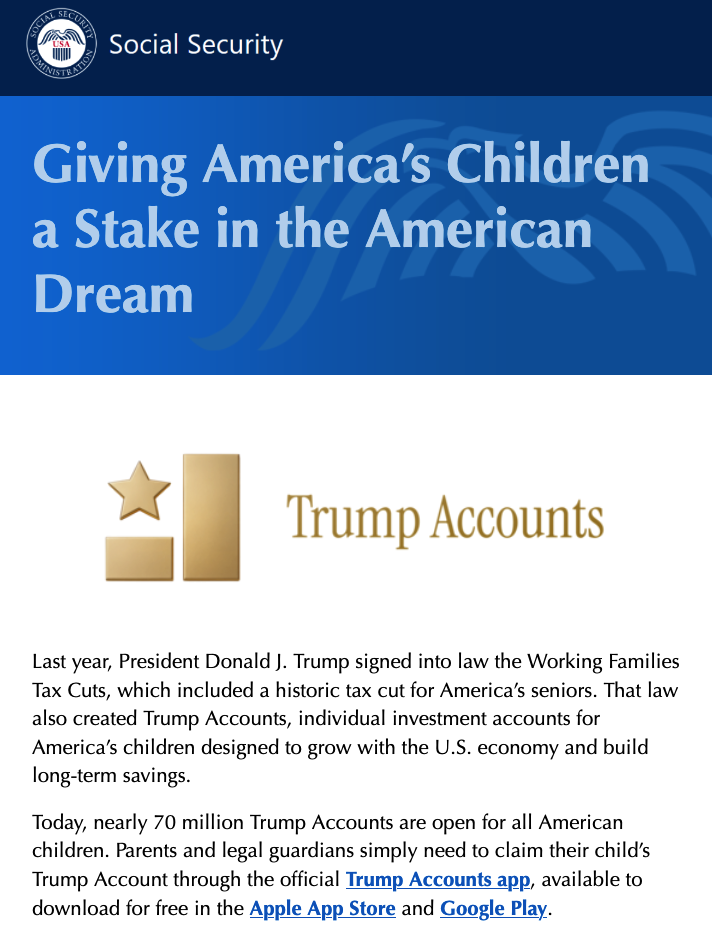
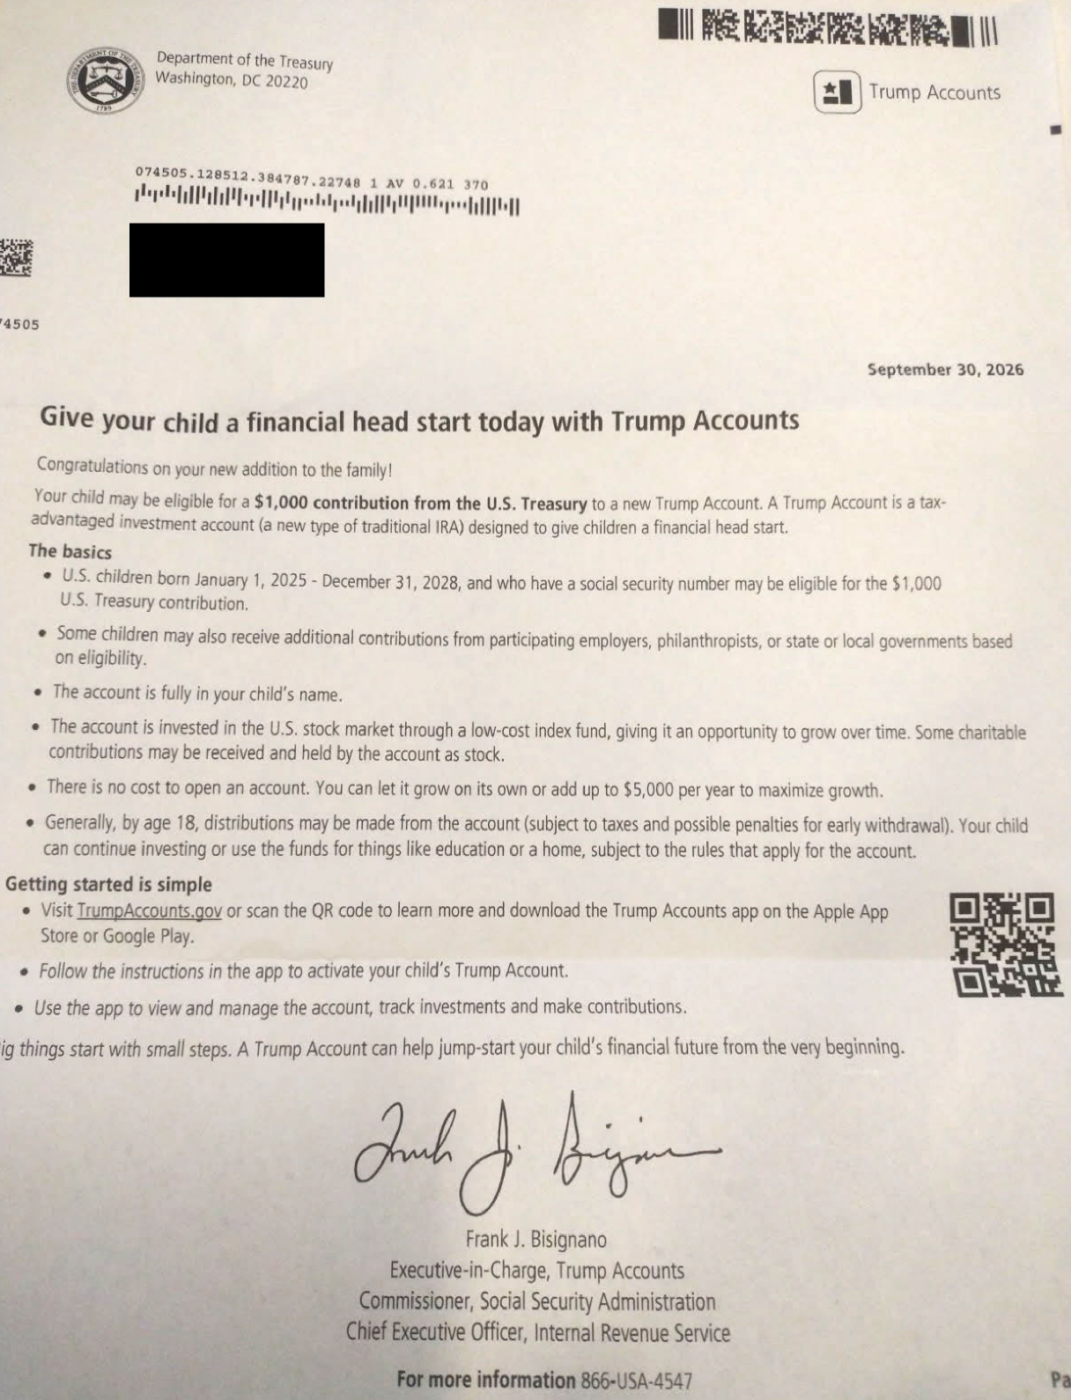
The next step for you, the parent/legal guardian, is to understand what these accounts are and how to claim them.
What They Are
A 530A account is essentially a starter-IRA for your child in which the child doesn’t need earned income to be eligible to receive contributions (as opposed to a Traditional or Roth IRA where they must have earned income). Here’s what you need to know.
The child is the beneficiary and legal owner of the account. Only one account is allowed per child. You (or another adult) are the responsible party and manage the account until the year the child turns 18, at which point it becomes a Traditional IRA owned by them. 530A accounts can receive a one-time seed contribution of $1,000 from the US Treasury if the child is a US citizen with valid SSN and born between January 1, 2025 and December 31, 2028. If eligible, you can accept this seed contribution while you’re claiming the account for the child. Alternatively, if you’ve already claimed the account you can complete IRS Form 4547 (download here) and submit it through the Trump Accounts App or Website to get the seed contribution.
Contributions to the account can come from any individual, in addition to the parent/guardian’s employer. Contributions from the parent, child, or other individual are made on an after-tax basis. Contributions from employers are made on a pre-tax basis. The annual contribution limit from these sources combined is $5,000 per child. The one-time seed contribution does not count toward this annual maximum. Contributions can only be invested in US stock mutual funds and/or ETFs. Most commonly, these will be index funds that track the S&P 500. This investment restriction goes away in the year the child turns 18.
Withdrawals are allowed starting in the year your child turns 18. However, withdrawals before 59 ½ incur a 10% early withdrawal penalty, unless they are qualified withdrawals for things like higher education or a first-time home purchase. These are the same rules that apply to other IRAs. Withdrawals of any pre-tax dollars (seed/employer contributions) and the investment earnings on any after-tax dollars (non-seed/non-employer contributions) after 59 ½ are subject to ordinary income tax but no penalty.
How to Claim
Parents/Legal Guardians can claim their child’s account through the Trump Accounts App or Website. You, the parent/guardian, will first create your login and complete the necessary verification steps. Next, you’ll enter your child’s information, where you can select to add another child if you have multiple. Then, you’ll review the information and will be asked to e-sign by typing your full name. This is the same process during which you can elect to receive the $1,000 seed contribution if the child is eligible. Once submitted, it typically takes anywhere from a few hours to a few days for your 530A account to be activated.
When to Use
Basically, 530As allow you to give your child a headstart on their long-term retirement savings during the years in which they don’t have earned income. However, it’s worth having a conversation with your financial planner to determine whether it makes sense to contribute to a 530A for your child. There are multiple different accounts that are designed to build savings for children, so knowing which ones to use for your specific situation is crucial. My colleague Luke wrote a post on the variety of kids savings accounts out there and how to think of each one. You can find that post HERE. For now, what’s important is that every parent/guardian claims their child’s 530A and, if eligible, elects to receive the $1,000 seed contribution.
Peter Kulseth, Investment Advisor
Peter is a native of San Juan Island. After graduating from Gonzaga University he moved to Seattle where he joined Bear Mountain. He cares deeply for his clients, helping them navigate their relationship with finances and everything that comes with it. Away from his desk he enjoys the fresh air of the Pacific Northwest by any means necessary – skiing, camping, playing basketball, and golfing.